Research Report
Hanwha Systems (272210 KS/Buy)Our top defense/aerospace pick
- Author Dong-ho Jeong
- Date Tue Apr 16 00:00:00 KST 2024
- Stock Code 272210
- File 20240416_Hanwha Systems (272210 KS_Buy).pdf
Our top defense/aerospace pick
1Q24 preview: OP to miss consensus by 19%
For 1Q24, we expect Hanwha Systems to report revenue of W495.9bn (+13% YoY; 1% below consensus) and operating profit of W18.7bn (+52% YoY; 19% below consensus). While seasonality likely weighed on 1Q24 earnings, the defense business should drive solid growth in 2024, backed by the recognition of Cheongung II multi-function radar exports to the UAE, the fourth round of Tactical Information Communication Network (TICN) mass production, and the mass production of 30mm wheeled anti-aircraft guns.
In 1H24, orders and events to be more important than earnings
We forecast new orders to exceed W4tr in 2024 (vs. W3.7tr in 2023), with around half of them likely to be awarded in 1H24. The defense division is poised to finalize mass production deals for Cheongung II multi-function radars (W1.7tr) and KF-21 AESA radars (W400-500bn) for Saudi Arabia. Additionally, downstream customers are expected to secure follow-up contracts with Romania and Poland this year. All in all, we believe the share of exports will increase (in terms of both orders and earnings) in 2024 and 2025, helping to establish a solid foundation for growth over the next five years.
A number of important events also lie ahead. In May, the Korea Aerospace Administration will be established, likely marking a turning point for the domestic aerospace industry. In addition, this year, the Defense Acquisition Program Administration plans to invest W150bn to advance core space technologies, such as next-generation reconnaissance satellites and military communication satellites. Meanwhile, Hanwha Systems plans to participate in an Australian next-generation communication system project (Land 4140), which should help lay the foundation for space cooperation and related exports to key countries. Additionally, Overair (Hanwha Systems’ partner) completed the assembly of its electric vertical take-off and landing (eVTOL) prototype (“Butterfly”) and is preparing for flight testing.
Maintain Buy and TP of W22,000
We maintain our Buy rating and target price of W22,000 on Hanwha Systems. The company is engaged in multiple promising future business areas, including defense, aerospace, and urban air mobility (UAM). While the company may need to invest heavily in R&D in the short term, we believe it stands out for its potential to build long-term value. Once new businesses such as UAM and ultra-small satellites (synthetic aperture radar satellites) start showing visible results, we believe they will serve as key drivers of additional momentum (alongside the defense unit).


Contact Us
- Office number1588-6800
-
- Investor Relationsirteam@miraeasset.com
- Human Resourcerecruit@miraeasset.com
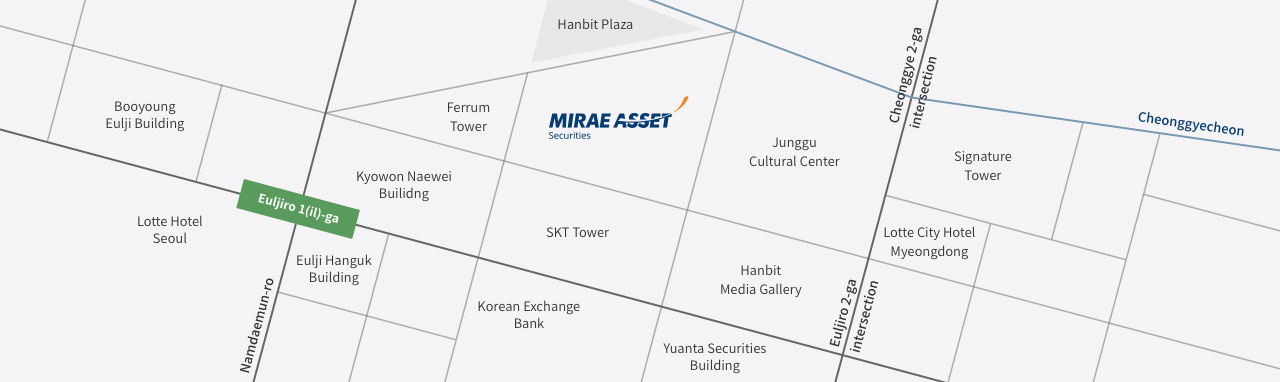
- AddressMirae Asset CENTER1 Bldg, East Tower, 26, Euljiro 5 gil, Jung-gu, Seoul 100-210
Korea (Headquarters)
Greece
Luxembourg
- Mirae Asset Global Investment(SICAV)
Mongolia
USA
- Mirae Asset Securities &
Investments Mirae Asset Securities(NY)
- Mirae Asset Global Investments
- Global X
- Mirae Asset Capital Life Science
- Wealthspot
Vietnam
- Mirae Asset Securities
- Mirae Asset Finance Company
- Mirae Asset Prevoir Life Insurance
- Mirae Asset Global Investments
- Vina Digital Finance Platform
- Grooo International Joint Stock
Company Mirae Asset Alternative
Invetment VietnamMirae Asset Securities
- Ho Chi Minh representative Ofiice
Brazil
Singapore
United Arab Emirates
Mirae Asset Investment Managers
- Dubai representative Office
Ireland
United Kingdom
India
Indonesia
Japan
China
- Mirae Asset Huachen Fund
Management Mirae Asset Investment
Management(Shanghai)Mirae Asset Securitires
(Beijing representative Office)Mirae Asset Securitires
(Shanghai representative Office)
Canada
Colombia
Australia
Hong Kong SAR*
Germany
Global X ETFs - Germany Rep Office
Italy
Global X ETFs - Italy Rep Office
* Special Administrative Region of the People’s Republic of China