Research Report
DB HiTek (000990 KS/Buy)Recovery to take some time
- Author Young-gun Kim
- Date Mon Dec 02 00:00:00 KST 2024
- Stock Code 000990
- File 20241202_DB HiTek (000990 KS_Buy).pdf
Recovery to take some time
Recommendation and valuation
We maintain our Buy rating on DB HiTek but cut our target price to W39,200 (from W57,000), applying a P/E of 8.7x to our 2025F EPS of W4,510. Our target multiple represents a 20% discount to the consensus 2025F P/E of United Microelectronics Corp. (UMC), which is trading at the lowest valuation among global peers. While DB HiTek’s stock has fallen to a 12-month forward P/B of 0.5x, we expect ROE (which is also at a historical low) to improve gradually from 2025. As concerns over weak market conditions appear to be fully priced in, we recommend accumulating shares from a medium- to long-term perspective.
Market conditions and investment points
While demand for AI chips is solid, we have yet to see a significant demand recovery for chips used in consumer electronics and industrial equipment (DB HiTek’s main products). Nevertheless, a number of players in the global semiconductor value chain note that inventory levels are improving, and there is a broad consensus that the industry is likely to enjoy solid growth over the medium/long term. As DB HiTek holds primary vendor status for over 80% of its customers, we think it is positioned to see the fastest recovery in orders (vs. peers) once demand picks up.
For 3Q24, the company posted revenue of W287.8bn (+7.5% YoY, -3.6% QoQ) and operating profit of W47bn (-6.4% YoY, -30% QoQ). Expectations for a market recovery had increased following solid results in 2Q24 (when revenue picked up 14% QoQ), but the improvement proved to be short-lived. In 3Q24, shipments stalled at 339,000 units (-0.2% QoQ), while ASP slid 2.3% QoQ. In 4Q24, we forecast revenue to decline 4.2% QoQ to W275.7bn and operating profit to fall 18% QoQ to W39bn amid a further fall in utilization.
On Oct. 11, the company announced plans to invest W250bn in facilities (e.g., clean rooms and utilities infrastructure) through Oct. 2027 in anticipation of potential capacity shortages. We believe this expansion will translate to additional wafer capacity of 30,000 units. As such, revenue could grow visibly once the new facilities are fully operational. While new businesses such as Si capacitors and GaN have experienced slight delays recently, the company is continuing R&D efforts to secure new growth drivers.


Contact Us
- Office number1588-6800
-
- Investor Relationsirteam@miraeasset.com
- Human Resourcerecruit@miraeasset.com
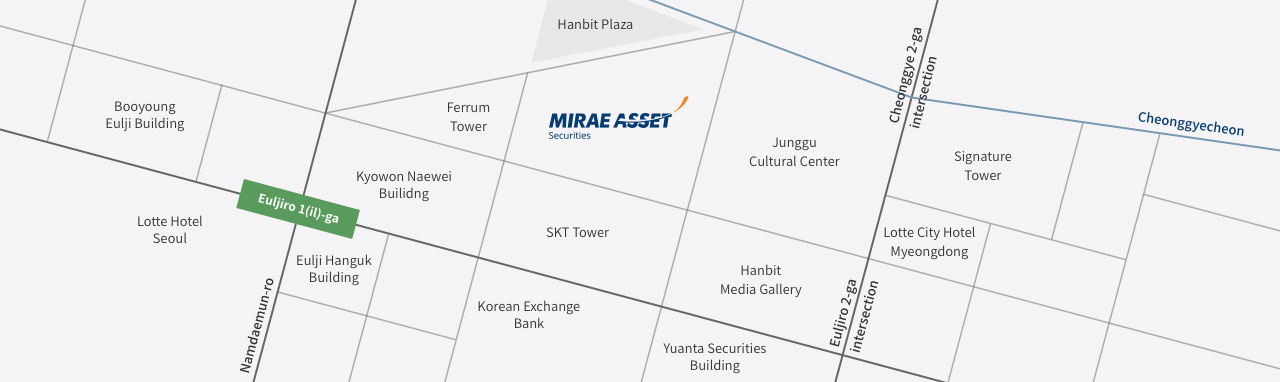
- AddressMirae Asset CENTER1 Bldg, East Tower, 26, Euljiro 5 gil, Jung-gu, Seoul 100-210
Korea (Headquarters)
Greece
Luxembourg
- Mirae Asset Global Investment(SICAV)
Mongolia
USA
- Mirae Asset Securities &
Investments Mirae Asset Securities(NY)
- Mirae Asset Global Investments
- Global X
- Mirae Asset Capital Life Science
- Wealthspot
Vietnam
- Mirae Asset Securities
- Mirae Asset Finance Company
- Mirae Asset Prevoir Life Insurance
- Mirae Asset Global Investments
- Vina Digital Finance Platform
- Grooo International Joint Stock
Company Mirae Asset Alternative
Invetment VietnamMirae Asset Securities
- Ho Chi Minh representative Ofiice
Brazil
Singapore
United Arab Emirates
Mirae Asset Investment Managers
- Dubai representative Office
Ireland
United Kingdom
India
Indonesia
Japan
China
- Mirae Asset Huachen Fund
Management Mirae Asset Investment
Management(Shanghai)Mirae Asset Securitires
(Beijing representative Office)Mirae Asset Securitires
(Shanghai representative Office)
Canada
Colombia
Australia
Hong Kong SAR*
Germany
Global X ETFs - Germany Rep Office
Italy
Global X ETFs - Italy Rep Office
* Special Administrative Region of the People’s Republic of China