Research Report
Samsung Electronics (005930 KS/Buy)Remarkable earnings and potential for additional shareholder returns
- Author Young-gun Kim
- Date Fri Jan 16 00:00:00 KST 2026
- Stock Code 005930
- File 20260116_Samsung Electronics (005930 KS_Buy).pdf
Remarkable earnings and potential for additional shareholder returns
Earnings up-cycle underway; shareholder returns to take center stage in 2026
We lift our target price for Samsung Electronics (SEC) by 21% to W187,000 (from W155,000). Using a sum-of-the-parts (SOTP) valuation, we estimate the company’s fair value at W1,271tr. Based on 2026F EPS and BPS, our target price implies a P/E of 11.6x and P/B of 2.6x, both of which remain below the 2026F global memory sector averages of 14.2x and 3.6x, respectively.
For 4Q25, SEC announced preliminary revenue of W93tr (+8.6% QoQ) and operating profit of W20tr (+67% QoQ). By division, we estimate operating profit at W16.7tr (+138% QoQ) for DS, W1.3tr (-63% QoQ) for DX, and W1.8tr (+50% QoQ) for Samsung Display. The memory business was the primary earnings driver (estimated profit contribution of W18tr), driven by strong price growth (+41% for DRAM, +25% for NAND).
For 2026, we look for revenue of W450tr (+35% YoY) and operating profit of W126tr (+186% YoY). We forecast memory operating profit to surge 250% YoY to W111tr, driving overall earnings growth. We project that bit growth will reach +27% for DRAM and +19% for NAND, with ASPs rising 59% and 31%, respectively.
Reasons for upbeat 2026 outlook
In 2026, SEC appears particularly well-positioned for several reasons. First, it is best positioned to benefit from sustained memory price strength due to its industry-leading production capacity. Commodity memory prices are expected to remain strong at least through 2026, while supplier inventories remain tight. As a result, output is being absorbed immediately. We estimate SEC’s average 2026 DRAM wafer capacity at 665,000 wpm, representing the largest share (41.5%) among the three major DRAM players. Reflecting this advantage, we removed the 10% discount that we previously applied to the memory business due to SEC’s competitive disadvantage in HBM.
Second, the foundry unit offers meaningful upside potential. We conservatively value the business at W43tr, applying a 30% discount due to limited near-term profitability. That said, we see multiple longer-term catalysts, including yield stabilization in 4nm HBM4 base dies, the adoption of the 2nm Exynos 2600 in some Galaxy S26 models, AI chip orders from Tesla and the full-scale operation of the Taylor fab, and the foundry’s strategic importance amid geopolitical uncertainty.
Lastly, SEC retains significant capacity for additional shareholder returns beyond its fixed payout policy. The firm has committed to returning 50% of three-year cumulative free cash flow (around W9.8tr per year) to shareholders, with the potential for additional special returns in the event of “meaningful” outperformance. In 2020, the firm paid out a special dividend of W1,578 per share from a W13.8tr special dividend pool, leading to a payout ratio of 78%. For 2026, we estimate the firm’s special dividend pool at W46.6tr; even assuming a payout ratio of only 40%, this could translate into an additional W5,080 per share. Based on the current share price, this implies a dividend yield of roughly 4.7% for common shares and 6.4% for preferred shares.


Contact Us
- Office number1588-6800
-
- Investor Relationsirteam@miraeasset.com
- Human Resourcerecruit@miraeasset.com
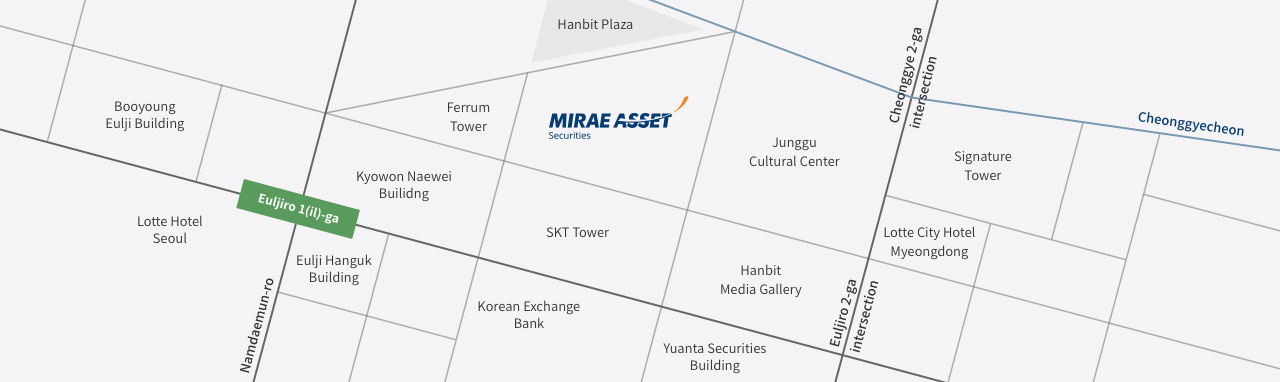
- AddressMirae Asset CENTER1 Bldg, East Tower, 26, Euljiro 5 gil, Jung-gu, Seoul 100-210
Korea (Headquarters)
Greece
Luxembourg
- Mirae Asset Global Investment(SICAV)
Mongolia
USA
- Mirae Asset Securities &
Investments Mirae Asset Securities(NY)
- Mirae Asset Global Investments
- Global X
- Mirae Asset Capital Life Science
- Wealthspot
Vietnam
- Mirae Asset Securities
- Mirae Asset Finance Company
- Mirae Asset Prevoir Life Insurance
- Mirae Asset Global Investments
- Vina Digital Finance Platform
- Grooo International Joint Stock
Company Mirae Asset Alternative
Invetment VietnamMirae Asset Securities
- Ho Chi Minh representative Ofiice
Brazil
Singapore
United Arab Emirates
Mirae Asset Investment Managers
- Dubai representative Office
Ireland
United Kingdom
India
Indonesia
Japan
China
- Mirae Asset Huachen Fund
Management Mirae Asset Investment
Management(Shanghai)Mirae Asset Securitires
(Beijing representative Office)Mirae Asset Securitires
(Shanghai representative Office)
Canada
Colombia
Australia
Hong Kong SAR*
Germany
Global X ETFs - Germany Rep Office
Italy
Global X ETFs - Italy Rep Office
* Special Administrative Region of the People’s Republic of China