Research Report
NCsoft (036570 KS/Buy)Look ahead to 2H26
- Author HeeSeok Lim
- Date Thu Feb 12 00:00:00 KST 2026
- Stock Code 036570
- File 20260212_NCsoft (036570 KS_Buy).pdf
Look ahead to 2H26
4Q25 review: Below-consensus results
For 4Q25, NCsoft reported revenue of W404bn (-1% YoY) and operating profit of W3bn (swinging to profit YoY), missing the consensus estimates (W427bn and W10bn, respectively). Aion 2 (launched in Korea and Taiwan in Nov. 2025) generated W94bn in gross revenue, but a portion of this was deferred, resulting in recognized revenue of W77bn. The title recorded average daily revenue of approximately W1.8bn. PC revenue came in at W168bn (+80% YoY), in line with expectations. However, legacy mobile titles underperformed, with Lineage M generating W94bn (-23% YoY; 14% below our estimate) and Lineage W generating W39bn (-21% YoY; 13% below our estimate). Operating expenses totaled W401bn (-26% YoY), broadly in line with expectations.
Stable performance from Aion 2
Following its November launch, Aion 2 has continued to deliver stable revenue in 1Q26, exceeding initial market expectations. From Jan. 1 to Feb. 10, the title generated approximately W70bn in revenue, translating to average daily revenue of roughly W1.7bn―largely in line with the level in 4Q25 shortly after launch (W1.8bn).
Even assuming that a meaningful downward stabilization in revenue begins in March, we expect the title to have little difficulty meeting market expectations (average daily revenue of W1.5bn in 1Q26 and W1bn in 2Q26). As of Feb. 9, 1.5mn users had purchased memberships (vs. 1mn as of Jan. 3). A high proportion of users are playing on PC, and the share of payments made through NCsoft’s in-house platform stands at approximately 80%.
Maintain Buy and TP of W280,000
With Aion 2 generating steady revenue in Korea and Taiwan, earnings expectations for 1H26 do not appear overly burdensome. That said, at a 2026F P/E of 16x, valuation does not look particularly attractive. Given the absence of major new title launches in 1H26, momentum is likely to remain subdued for the time being. While Lineage Classic was released in February, it is unlikely to contribute significantly to revenue growth.
We expect a more attractive entry point to emerge around June, when momentum related to the global launch of Aion 2 should begin building. The company previously achieved strong early traction with the global launch of Throne and Liberty, and we expect Aion 2 to benefit from similarly strong launch momentum. With management announcing a 3Q26 release target, we believe the title remains on track for a fall launch


Contact Us
- Office number1588-6800
-
- Investor Relationsirteam@miraeasset.com
- Human Resourcerecruit@miraeasset.com
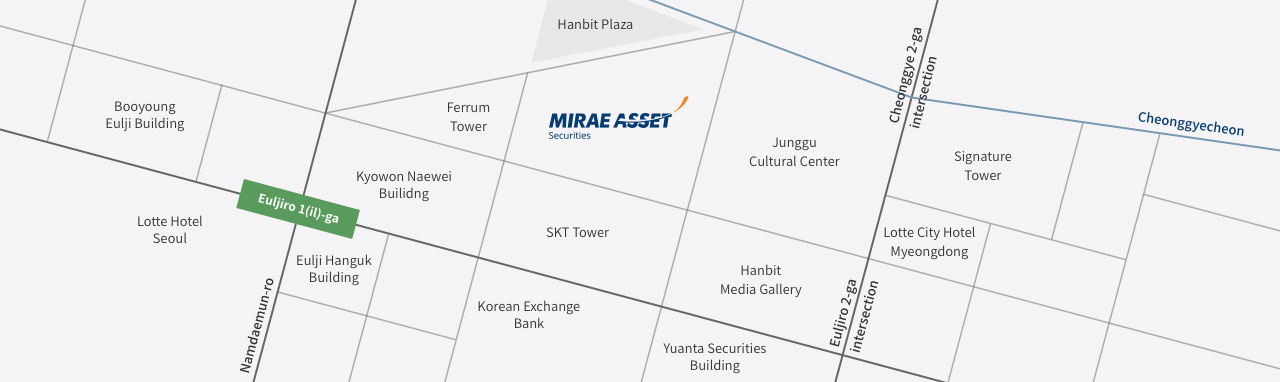
- AddressMirae Asset CENTER1 Bldg, East Tower, 26, Euljiro 5 gil, Jung-gu, Seoul 100-210
Korea (Headquarters)
Greece
Luxembourg
- Mirae Asset Global Investment(SICAV)
Mongolia
USA
- Mirae Asset Securities &
Investments Mirae Asset Securities(NY)
- Mirae Asset Global Investments
- Global X
- Mirae Asset Capital Life Science
- Wealthspot
Vietnam
- Mirae Asset Securities
- Mirae Asset Finance Company
- Mirae Asset Prevoir Life Insurance
- Mirae Asset Global Investments
- Vina Digital Finance Platform
- Grooo International Joint Stock
Company Mirae Asset Alternative
Invetment VietnamMirae Asset Securities
- Ho Chi Minh representative Ofiice
Brazil
Singapore
United Arab Emirates
Mirae Asset Investment Managers
- Dubai representative Office
Ireland
United Kingdom
India
Indonesia
Japan
China
- Mirae Asset Huachen Fund
Management Mirae Asset Investment
Management(Shanghai)Mirae Asset Securitires
(Beijing representative Office)Mirae Asset Securitires
(Shanghai representative Office)
Canada
Colombia
Australia
Hong Kong SAR*
Germany
Global X ETFs - Germany Rep Office
Italy
Global X ETFs - Italy Rep Office
* Special Administrative Region of the People’s Republic of China