Research Report
Amorepacific (090430 KS/Buy)Solid earnings delivery
- Author Songyi Bae
- Date Thu Apr 30 00:00:00 KST 2026
- Stock Code 090430
- File 20260430_Amorepacific (090430 KS_Buy).pdf
Solid earnings delivery
1Q26 review: Domestic leverage accelerating; overseas brand portfolio growing
For 1Q26, Amorepacific posted revenue of W1.14tr (+6% YoY) and operating profit of W126.7bn (+8% YoY), in line with expectations. Stronger-than-expected operating leverage in the domestic market (operating profit growth of 65% YoY and OP margin of 13%) helped offset increased marketing spending overseas.
The domestic business stood out, with revenue of W626.4bn (+9% YoY) and operating profit of W81.5bn (+65% YoY). Growth (YoY) was broad-based across all segments (+6% for luxury, +20% for premium, and +12% for daily beauty) and channels (+9% for pure domestic and +8% for duty-free/cross-border operations). Increased inbound tourism and solid domestic consumption likely had a meaningful impact on earnings, given the company’s higher domestic exposure relative to K-beauty peers. The sharp growth in operating profit was driven by both top-line expansion and improved cost efficiency.
Meanwhile, overseas results were slightly disappointing, with revenue of W497.1bn (+6% YoY) and operating profit of W56.7bn (-18% YoY). Revenue was weighed down by weaker sell-in for the flagship brand Laneige in Western markets. However, sell-out trends remained relatively healthy, and momentum appears solid for brands being nurtured as next-generation growth engines (triple-digit growth for Aestura and rollout of Iope). Accordingly, we expect growth rates to recover from 2Q26.
Overseas profits declined due to increased investments aimed at fostering the next flagship brand. Marketing expenses increased by W24.2bn (+20% YoY), and a significant portion of the marketing spend appears to have been allocated to newly launched brands in Western markets. Within these markets, we estimate the revenue contribution by brand at over 30% each for COSRX and Laneige, with emerging brands such as Aestura, Sulwhasoo, and Innisfree each accounting for less than 10%. We expect investments to continue until these brands establish a stable foothold.
Strengthening portfolio competitiveness
While rising competition for Laneige―the key driver of overseas growth―is a concern, the company continues to post resilient earnings through improved domestic fundamentals and is actively investing to build multiple future growth drivers, which we view as a sound strategic approach for a company managing a diversified brand portfolio. The full-scale turnaround of COSRX is also encouraging.
That said, we believe it will take time for emerging brands to contribute meaningfully to earnings. We also do not see significant valuation appeal, with the stock trading at a 12-month forward P/E of 23x. We anticipate a renewed pickup in momentum once emerging brands begin to deliver meaningful results.


Contact Us
- Office number1588-6800
-
- Investor Relationsirteam@miraeasset.com
- Human Resourcerecruit@miraeasset.com
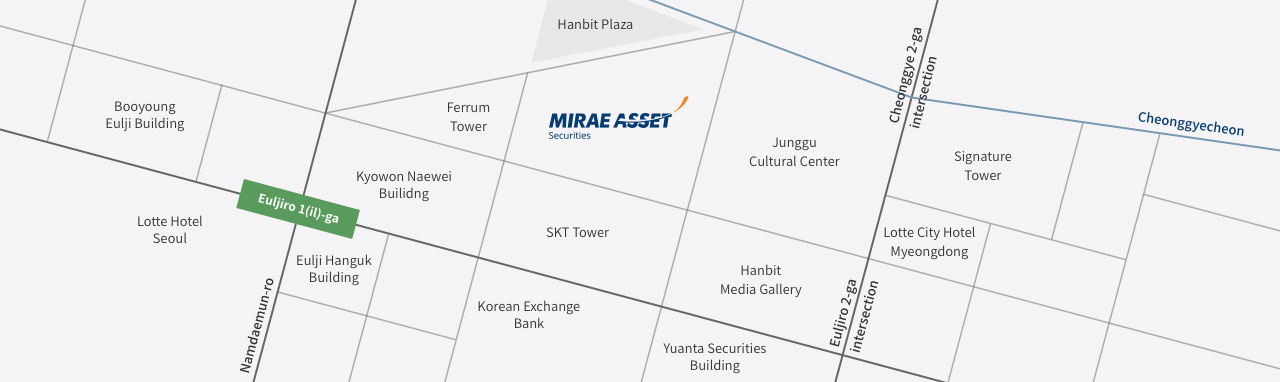
- AddressMirae Asset CENTER1 Bldg, East Tower, 26, Euljiro 5 gil, Jung-gu, Seoul 100-210
Korea (Headquarters)
Greece
Luxembourg
- Mirae Asset Global Investment(SICAV)
Mongolia
USA
- Mirae Asset Securities &
Investments Mirae Asset Securities(NY)
- Mirae Asset Global Investments
- Global X
- Mirae Asset Capital Life Science
- Wealthspot
Vietnam
- Mirae Asset Securities
- Mirae Asset Finance Company
- Mirae Asset Prevoir Life Insurance
- Mirae Asset Global Investments
- Vina Digital Finance Platform
- Grooo International Joint Stock
Company Mirae Asset Alternative
Invetment VietnamMirae Asset Securities
- Ho Chi Minh representative Ofiice
Brazil
Singapore
United Arab Emirates
Mirae Asset Investment Managers
- Dubai representative Office
Ireland
United Kingdom
India
Indonesia
Japan
China
- Mirae Asset Huachen Fund
Management Mirae Asset Investment
Management(Shanghai)Mirae Asset Securitires
(Beijing representative Office)Mirae Asset Securitires
(Shanghai representative Office)
Canada
Colombia
Australia
Hong Kong SAR*
Germany
Global X ETFs - Germany Rep Office
Italy
Global X ETFs - Italy Rep Office
* Special Administrative Region of the People’s Republic of China