Research Report
LG Chem (051910 KS/Buy)Profitability to improve through 2Q26
- Author Jinho Lee
- Date Mon May 04 00:00:00 KST 2026
- Stock Code 051910
- File 20260504_LG Chem (051910 KS_Buy).pdf
Profitability to improve through 2Q26
Raise TP to W480,000; maintain Buy
We maintain our Buy rating on LG Chem and raise our target price to W480,000 (from W430,000), reflecting an upward revision to our 2026 earnings forecast for the petrochemicals division. Although the favorable feedstock inventory lag seen in 1Q26 should fade, improved spreads should support profitability in 2Q26. Meanwhile, we expect the cathode materials business to gradually recover, with 4Q26 shipments likely to return to 2024 levels (over 20,000 tonnes per quarter) on the back of new North American volumes. Overall, we remain positive on the company’s improving earnings resilience. That said, once the easing of geopolitical risks is confirmed and product prices gradually decline, negative inventory lagging effects could pose a downside risk to earnings.
1Q26 review: Petrochemicals outperform
For 1Q26, LG Chem posted an operating loss of W49.7bn, outperforming the consensus (-W160.7bn). On a standalone basis (excluding the battery business), operating profit came in at W158.0bn. The beat was primarily driven by stronger-than-expected results in the petrochemicals division, which benefited from a favorable inventory lag from naphtha and other feedstocks (W80?100bn) and the refund of European antidumping duties (W40?50bn). Meanwhile, advanced materials earnings were broadly in line with the 4Q25 level, while life sciences and Farm Hannong earnings picked up slightly QoQ. In the battery segment, while the increase in ESS shipment volumes was positive, losses widened due to initial ramp-up costs at ESS plants and an unfavorable product mix.
2Q26 preview: Recovery in batteries and cathode materials
For 2Q26, we expect LG Chem to post consolidated operating profit of W415bn (turning positive QoQ) and standalone operating profit of W181bn (+14% QoQ). The battery segment is likely to deliver the sharpest improvement. Outside of batteries, we expect advanced materials to be the main driver of standalone earnings growth. After bottoming in 4Q25, cathode materials utilization is gradually recovering and expected to reach roughly 30?40% in 2Q26. As a result, fixed cost pressures are likely to ease, helping to narrow losses. In petrochemicals, despite the shutdown of the Yeosu NCC no. 2 plant, we expect profitability to remain broadly stable through optimized utilization across the remaining NCC facilities.


Contact Us
- Office number1588-6800
-
- Investor Relationsirteam@miraeasset.com
- Human Resourcerecruit@miraeasset.com
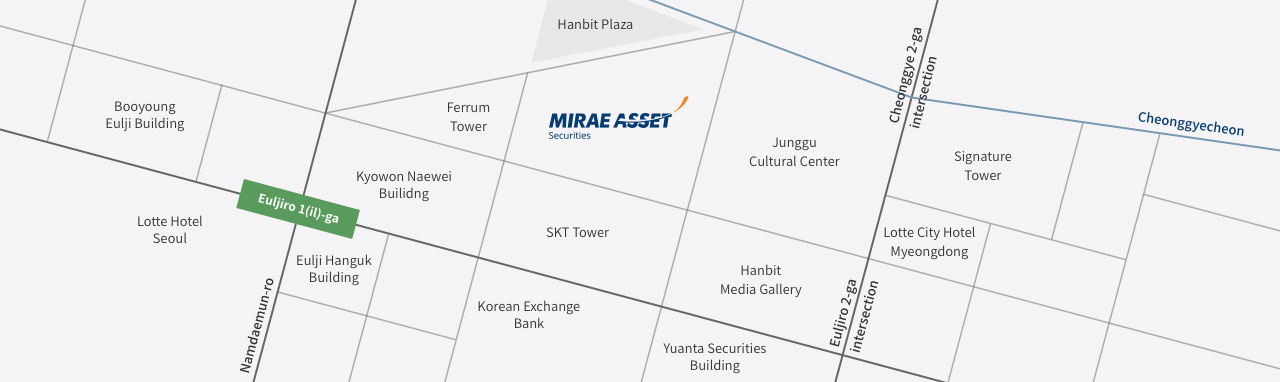
- AddressMirae Asset CENTER1 Bldg, East Tower, 26, Euljiro 5 gil, Jung-gu, Seoul 100-210
Korea (Headquarters)
Greece
Luxembourg
- Mirae Asset Global Investment(SICAV)
Mongolia
USA
- Mirae Asset Securities &
Investments Mirae Asset Securities(NY)
- Mirae Asset Global Investments
- Global X
- Mirae Asset Capital Life Science
- Wealthspot
Vietnam
- Mirae Asset Securities
- Mirae Asset Finance Company
- Mirae Asset Prevoir Life Insurance
- Mirae Asset Global Investments
- Vina Digital Finance Platform
- Grooo International Joint Stock
Company Mirae Asset Alternative
Invetment VietnamMirae Asset Securities
- Ho Chi Minh representative Ofiice
Brazil
Singapore
United Arab Emirates
Mirae Asset Investment Managers
- Dubai representative Office
Ireland
United Kingdom
India
Indonesia
Japan
China
- Mirae Asset Huachen Fund
Management Mirae Asset Investment
Management(Shanghai)Mirae Asset Securitires
(Beijing representative Office)Mirae Asset Securitires
(Shanghai representative Office)
Canada
Colombia
Australia
Hong Kong SAR*
Germany
Global X ETFs - Germany Rep Office
Italy
Global X ETFs - Italy Rep Office
* Special Administrative Region of the People’s Republic of China