Research Report
SK Telecom (017670 KS/Buy)Cost efficiency and full-stack AI capabilities to drive profitability improvement
- Author YooJin Choi
- Date Fri May 08 00:00:00 KST 2026
- Stock Code 017670
- File 20260508_SK Telecom (017670 KS_Buy).pdf
Cost efficiency and full-stack AI capabilities to drive profitability improvement
1Q26 review: Return to net handset subscriber additions; dividends resume
For 1Q26, SK Telecom (SKT) reported in-line results, with consolidated revenue of roughly W4.4tr (-1.4% YoY) and operating profit of W537.6bn (-5.3% YoY).
Handset subscribers returned to net additions (+208,000). The number of 5G subscribers rose 3.2% YoY to 17.8mn, bringing 5G penetration to 81.1% and SKT’s 5G market share to 46.4%. Meanwhile, as earnings entered a more normalized phase, the company resumed quarterly dividends with a DPS of W830.
SK Broadband reported revenue of W1.1tr (+3.2% YoY) and operating profit of W116.6bn (+21.4% YoY). The strong results were driven by higher utilization at the Gasan and Pangyo data centers as well as expanding GPU-as-a-Service (GPUaaS) revenue, with AI data center revenue jumping 89.3% YoY to W131.4bn.
2026 outlook: Margins to improve on cost efficiency and full-stack AI capabilities
For 2026, we look for revenue of around W18tr (+5.1% YoY) and operating profit of W1.9tr (+81.5% YoY). Efforts to improve cost efficiency should continue to support earnings growth. Competition is likely to remain relatively limited, leading to only a modest rise in full-year marketing expenses (estimated at W3.4tr; +1.7% YoY). Depreciation expenses should also continue to trend downward amid the earnings recovery cycle. We forecast 2026 DPS at W3,540 (+113% YoY).
We believe SKT’s unique full-stack AI capabilities―spanning infrastructure, models, and services―should increasingly translate into monetization opportunities. Going forward, we expect AI-related top-line growth to be supported by: 1) the construction of a roughly 100MW hyperscale data center in Ulsan; 2) service expansion based on sovereign AI; and 3) the A. (AI assistant) service.
Raise TP by 22% to W120,000; our top pick in the sector
We maintain our Buy rating on SKT and raise our target price by 22% to W120,000 (from W98,000). Our target price is based on the sum of SKT’s operating value (W22tr) and the value of its stake in Anthropic (W3.2tr). We maintain the stock as our top pick in the sector.


Contact Us
- Office number1588-6800
-
- Investor Relationsirteam@miraeasset.com
- Human Resourcerecruit@miraeasset.com
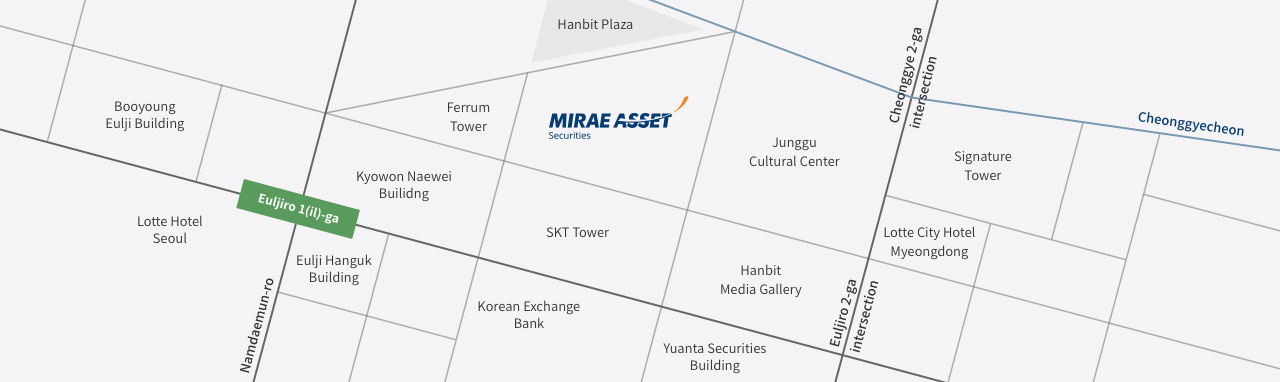
- AddressMirae Asset CENTER1 Bldg, East Tower, 26, Euljiro 5 gil, Jung-gu, Seoul 100-210
Korea (Headquarters)
Greece
Luxembourg
- Mirae Asset Global Investment(SICAV)
Mongolia
USA
- Mirae Asset Securities &
Investments Mirae Asset Securities(NY)
- Mirae Asset Global Investments
- Global X
- Mirae Asset Capital Life Science
- Wealthspot
Vietnam
- Mirae Asset Securities
- Mirae Asset Finance Company
- Mirae Asset Prevoir Life Insurance
- Mirae Asset Global Investments
- Vina Digital Finance Platform
- Grooo International Joint Stock
Company Mirae Asset Alternative
Invetment VietnamMirae Asset Securities
- Ho Chi Minh representative Ofiice
Brazil
Singapore
United Arab Emirates
Mirae Asset Investment Managers
- Dubai representative Office
Ireland
United Kingdom
India
Indonesia
Japan
China
- Mirae Asset Huachen Fund
Management Mirae Asset Investment
Management(Shanghai)Mirae Asset Securitires
(Beijing representative Office)Mirae Asset Securitires
(Shanghai representative Office)
Canada
Colombia
Australia
Hong Kong SAR*
Germany
Global X ETFs - Germany Rep Office
Italy
Global X ETFs - Italy Rep Office
* Special Administrative Region of the People’s Republic of China