Research Report
Kumho Petrochemical (011780 KS/Buy)Meaningful spread improvement likely as feedstock prices stabilize
- Author Jinho Lee
- Date Fri May 08 00:00:00 KST 2026
- Stock Code 011780
- File 20260508_Kumho Petrochemical (011780 KS_Buy).pdf
Meaningful spread improvement likely as feedstock prices stabilize
Lift TP to W160,000 and upgrade to Buy
We raise our target price for Kumho Petrochemical from W144,000 to W160,000, reflecting upward revisions to our 2Q26 earnings forecasts. Although the company had been gradually recovering from the 2025 market slump arising from severe NB latex oversupply, the surge in butadiene prices following the outbreak of the Middle East conflict disrupted the recovery, weighing on 1Q26 results. Since April, however, we have seen meaningful pass-through of higher feedstock prices to selling prices, while feedstock prices have also begun to stabilize. With earnings improvement likely to accelerate in 2Q26, we upgrade our rating on the stock to Buy (from Hold).
1Q26 review: OP misses consensus by a wide margin
For 1Q26, Kumho Petrochemical reported operating profit of W59.4bn, falling 12% short of the consensus (W67.4bn). The miss was driven by the sharp rise in butadiene prices stemming from the Middle East conflict, as well as cautious purchasing behavior by downstream customers. Profitability in synthetic rubber had improved in January-February, but after the outbreak of the conflict in March, butadiene prices surged from US$1,300/tonne to US$2,700/tonne, sharply increasing costs (which the company could not quickly pass through to product prices). That said, all segments other than synthetic rubber showed QoQ earnings improvement.
2Q26 preview: Earnings improvement expected across all segments
For 2Q26, we forecast operating profit to climb sharply QoQ to W112.2bn (vs. W59.4bn in 1Q26). We expect the largest improvement to come from the synthetic rubber segment, where cost pass-through is now gaining traction. Although butadiene prices remain highly volatile, they have recently been stabilizing below US$2,000/tonne. In addition, NB latex prices began to surge in April and have since more than doubled, suggesting that spreads are likely to show marked improvement. Meanwhile, market conditions for synthetic resin and phenol derivatives (which had been weak) are also improving, as recent supply shortages have supported pricing; as such, we expect both segments to swing to profit. For the EPDM/TPV and energy/other businesses, we expect utilization to decline due to routine maintenance, but profitability should remain stable.


Contact Us
- Office number1588-6800
-
- Investor Relationsirteam@miraeasset.com
- Human Resourcerecruit@miraeasset.com
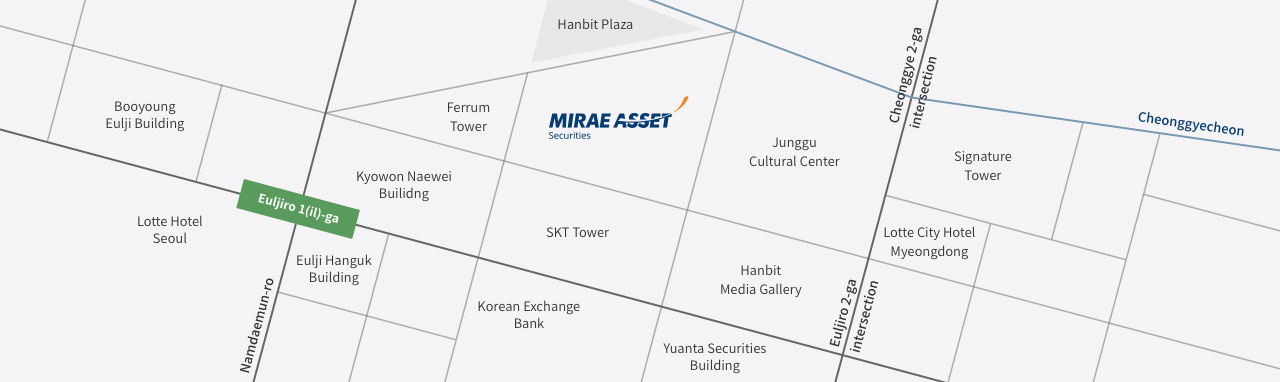
- AddressMirae Asset CENTER1 Bldg, East Tower, 26, Euljiro 5 gil, Jung-gu, Seoul 100-210
Korea (Headquarters)
Greece
Luxembourg
- Mirae Asset Global Investment(SICAV)
Mongolia
USA
- Mirae Asset Securities &
Investments Mirae Asset Securities(NY)
- Mirae Asset Global Investments
- Global X
- Mirae Asset Capital Life Science
- Wealthspot
Vietnam
- Mirae Asset Securities
- Mirae Asset Finance Company
- Mirae Asset Prevoir Life Insurance
- Mirae Asset Global Investments
- Vina Digital Finance Platform
- Grooo International Joint Stock
Company Mirae Asset Alternative
Invetment VietnamMirae Asset Securities
- Ho Chi Minh representative Ofiice
Brazil
Singapore
United Arab Emirates
Mirae Asset Investment Managers
- Dubai representative Office
Ireland
United Kingdom
India
Indonesia
Japan
China
- Mirae Asset Huachen Fund
Management Mirae Asset Investment
Management(Shanghai)Mirae Asset Securitires
(Beijing representative Office)Mirae Asset Securitires
(Shanghai representative Office)
Canada
Colombia
Australia
Hong Kong SAR*
Germany
Global X ETFs - Germany Rep Office
Italy
Global X ETFs - Italy Rep Office
* Special Administrative Region of the People’s Republic of China