Research Report
Hanmi Pharm (128940 KS/Buy)Eli Lilly deal adds to pipeline value
- Author Seung-min Kim
- Date Thu Jun 04 00:00:00 KST 2026
- Stock Code 128940
- File 20260604_Hanmi Pharm (128940 KS_Buy).pdf
Eli Lilly deal adds to pipeline value
Raise TP to W700,000 (from W660,000); maintain Buy
Our target price for Hanmi Pharm is based on an operating value estimate of W5.9tr (vs. W6.1tr previously) and a pipeline value estimate of W3.1tr (vs. W2.5tr previously). While our earnings forecasts for the core business (excluding licensing-related up-front payments) remain unchanged, we lowered our target EV/EBITDA to 14.6x (from 16.4x) to reflect a decline in the average multiple of leading domestic pharmas (driven by generic drug price cuts in Korea and the sector’s relative underperformance vs. market-leading sectors). For our pipeline value estimate, we added W524.9bn for the GLP-2 analog sonefpeglutide, which was out-licensed to Eli Lilly. Given that Eli Lilly is the global leader in metabolic disease therapies, we think the prospects for clinical development, indication expansion, and commercial success are substantially stronger than they would be with other partners. The out-licensing deal was a positive surprise, as expectations for the asset had been relatively low. In addition, there remain opportunities for further out-licensing deals (HM15275, HM17321, HM15136, etc.). Looking to 2H26, key events to watch include: 1) the phase 2b data release for efinopegdutide in MASH (Merck); 2) domestic approval/launch of efpeglenatide; 3) phase 1 single ascending dose data for HM17321 (obesity); and 4) phase 2 data for HM15136 in congenital hyperinsulinism.
W1.9tr licensing deal with Eli Lilly, including roughly W110bn up-front payment
In its phase 1 study, sonefpeglutide demonstrated: 1) a long-acting profile, with a mean half-life of 108?167 hours; 2) a favorable safety profile and low immunogenicity; 3) plasma citrulline-based pharmacodynamic effects that persisted for up to 30 days after dosing; and 4) pharmacokinetic characteristics that were unaffected by renal impairment. These results support its potential as a next-generation treatment for short bowel syndrome (SBS) with once-monthly dosing, and the asset is currently in a phase 2 trial. Teduglutide (marketed by Takeda as Gattex/Revestive), a commercialized GLP-2 analog for SBS, requires once-daily administration and achieved peak annual sales of approximately US$1bn. While the SBS market may appear relatively small, we believe sonefpeglutide could unlock a significantly larger commercial opportunity if it demonstrates clear advantages over existing therapies in terms of dosing convenience, long-acting efficacy, and safety. We estimate its peak annual sales potential at around US$3bn. As illustrated in the diabetes market, improved dosing convenience within the same therapeutic class can significantly enhance market penetration and commercial potential; Victoza, a once-daily GLP-1 therapy, achieved peak annual sales of around US$4bn, while Ozempic, a once-weekly formulation, has grown into a product generating roughly US$20bn in annual sales. We believe sonefpeglutide has substantial medium/long-term pipeline value, given its potential to not only reshape the treatment paradigm for SBS but also expand into adjacent indications where GLP-2-based therapies may be effective.


Contact Us
- Office number1588-6800
-
- Investor Relationsirteam@miraeasset.com
- Human Resourcerecruit@miraeasset.com
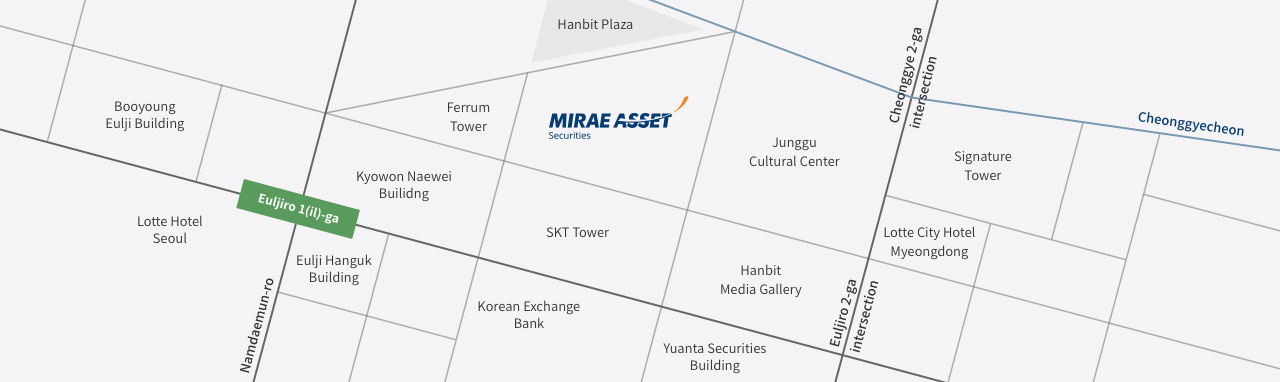
- AddressMirae Asset CENTER1 Bldg, East Tower, 26, Euljiro 5 gil, Jung-gu, Seoul 100-210
Korea (Headquarters)
Greece
Luxembourg
- Mirae Asset Global Investment(SICAV)
Mongolia
USA
- Mirae Asset Securities &
Investments Mirae Asset Securities(NY)
- Mirae Asset Global Investments
- Global X
- Mirae Asset Capital Life Science
- Wealthspot
Vietnam
- Mirae Asset Securities
- Mirae Asset Finance Company
- Mirae Asset Prevoir Life Insurance
- Mirae Asset Global Investments
- Vina Digital Finance Platform
- Grooo International Joint Stock
Company Mirae Asset Alternative
Invetment VietnamMirae Asset Securities
- Ho Chi Minh representative Ofiice
Brazil
Singapore
United Arab Emirates
Mirae Asset Investment Managers
- Dubai representative Office
Ireland
United Kingdom
India
Indonesia
Japan
China
- Mirae Asset Huachen Fund
Management Mirae Asset Investment
Management(Shanghai)Mirae Asset Securitires
(Beijing representative Office)Mirae Asset Securitires
(Shanghai representative Office)
Canada
Colombia
Australia
Hong Kong SAR*
Germany
Global X ETFs - Germany Rep Office
Italy
Global X ETFs - Italy Rep Office
* Special Administrative Region of the People’s Republic of China