Research Report
[2H26 Outlook] Pharma/BiotechCatalysts for a biotech rebound
- Author Seung-min Kim
- Date Thu Jun 18 00:00:00 KST 2026
- Stock Code 000100 / 006280 / 009420 / 024850 / 028300 / 039200 / 068270 / 069620 / 128940 / 141080 / 185750 / 196170 / 226950 / 298380 / 326030 / 347850 / 358570 / 397030 / 475830 / 950160
- File 20260618_[2H26 Outlook] Pharma_Biotech.pdf
Biotech stocks performed well early this year, driven by optimism surrounding the government''s KOSDAQ 3,000 target and supportive fund flows following the launch of multiple active ETFs. Since then, however, the sector has materially underperformed the broader market amid a lack of tangible achievements and diminishing relative appeal vs. the IT sector. Company-specific setbacks--including Sam Chun Dang Pharm’s loss of investor confidence and sharp share price decline, reduced expectations for Alteogen following the disclosure of its royalty rate, delays to phase 2 initiation for ABL Bio’s ABL301, and the overall survival (OS) miss for tovecimig--have also weighed on sentiment.
However, a number of positive developments have emerged in June: 1) D&D Pharmatech released exceptionally strong data for its MASH candidate; 2) Immunovant (partner of HanAll Biopharma) released highly encouraging data in difficult-to-treat rheumatoid arthritis (D2T RA); 3) Curevo, an affiliate of GC Biopharma, was acquired by Eli Lilly; and 4) OliX Pharmaceuticals secured an investment from L’Oreal. Meanwhile, global pharma M&A/licensing activity remains exceptionally robust and is expected to approach record highs in 2026. While 1H26 transactions mostly involved US and Chinese companies, June has seen agreements involving domestic firms such as Hanmi Pharm and Oscotec. Against this backdrop, we believe Korean biotech firms are well-positioned to deliver meaningful R&D achievements in 2H26.
In MASH and metabolic diseases, D&D Pharmatech bears watching, given its positive 48-week biopsy data, while OliX Pharmaceuticals is advancing its mARC1-targeting siRNA program (phase 1 completion and phase 2 entry expected). In central nervous system (CNS) disorders, ABL Bio’s BBB shuttle platform Grabody-B remains an area to monitor. Although phase 2 initiation for ABL301, which is based on Grabody-B, has been delayed, this is believed to be an asset-specific issue. In oncology, LigaChem Biosciences remains our preferred name, with several partners scheduled to release interim data and its Trop2 ADC program progressing as planned. Meanwhile, Orum Therapeutics is expected to provide interim phase 1 data updates for ORM-6151 and file an IND for ORM-1153. In immunology and inflammation, we favor HanAll Biopharma, as upcoming proof-of-concept data for IMVT-1402 in cutaneous lupus erythematosus (CLE) and additional data from the D2T RA trial could serve as potential catalysts.
From an earnings perspective, we focus on four areas: commercialized novel drugs, CDMOs, biosimilars, and domestic pharmaceutical companies. Within commercialized drugs, Yuhan deserves attention, as the potential release of final OS data on the Lazcluze-Rybrevant combo therapy in 2H26 could support further penetration into the first-line treatment market for EGFR-mutated non-small cell lung cancer (NSCLC). For SK Biopharmaceuticals, a competing product (azetukalner) has shown impressive clinical results, but given its expected launch timing (4Q27/1Q28), we do not view it as a meaningful threat to Xcopri’s growth trajectory. Celltrion’s Zymfentra is maintaining steady growth in US prescriptions, fueled by broader formulary coverage. As for Alteogen, prescription growth for Keytruda Qlex (which incorporates Alteogen''s ALT-B4 technology) is raising the possibility of sales milestone payments from Merck as early as 2Q26.
In the CDMO space, labor disputes at Samsung Biologics remain unresolved; some top-line impact appears unavoidable due to disruptions to certain production processes, and even after negotiations are concluded, labor costs are likely to increase. In addition, excluding volumes announced in connection with the acquisition of GSK''s manufacturing facility, the company has not disclosed meaningful new orders for approximately nine months. On the positive side, recent regulatory developments affecting WuXi could create opportunities for competing CDMO players; in June, the US Department of Defense added WuXi AppTec (non-antibody CDMO) to its Section 1260H list of Chinese military companies. Investors should monitor whether WuXi Biologics (antibody CDMO) is eventually added to the same list.
The market environment for biosimilars is becoming increasingly favorable. Regulators in major markets, including the US and Europe, are moving toward streamlined biosimilar development pathways (including through the elimination of phase 3 trials), which should reduce development costs for established players such as Celltrion and Samsung Bioepis. While simplified requirements could encourage new entrants and intensify competition, we believe biosimilar manufacturers will continue to capture share from original products, and industry leaders with manufacturing scale and cost advantages should further strengthen their competitive positions.
For domestic pharmaceutical companies, earnings remain vulnerable to generic drug price cuts in Korea. As a result, growth drivers outside of traditional prescription drug products will be increasingly important. Key areas to watch include Yuhan’s API business (through Yuhan Chemical), Hanmi Pharm’s Beijing Hanmi operations and domestic commercialization of novel obesity treatments, Daewoong Pharmaceutical’s Nabota exports and digital healthcare initiatives, and Chong Kun Dang’s pipeline development.
Overall, from an earnings perspective, we recommend focusing on Celltrion and Hanmi Pharm. For Celltrion, we anticipate both top-line growth and margin expansion driven by continued growth in Zymfentra prescriptions, a favorable environment for biosimilars, and contributions from newly launched biosimilars. For Hanmi Pharm, the approval and launch of efpeglenatide in Korea are expected in 2H26, and earnings should benefit from the recognition of revenue related to the out-licensing of sonefpeglutide. Clinical progress for the firm’s triple-agonist obesity candidate and phase 1 single ascending dose data for its muscle-preserving UCN2 candidate also warrant attention.


Contact Us
- Office number1588-6800
-
- Investor Relationsirteam@miraeasset.com
- Human Resourcerecruit@miraeasset.com
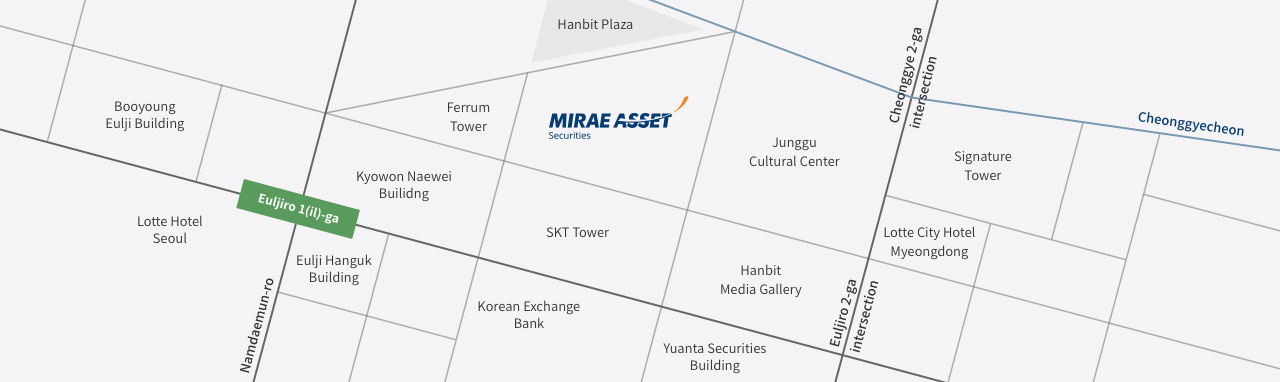
- AddressMirae Asset CENTER1 Bldg, East Tower, 26, Euljiro 5 gil, Jung-gu, Seoul 100-210
Korea (Headquarters)
Greece
Luxembourg
- Mirae Asset Global Investment(SICAV)
Mongolia
USA
- Mirae Asset Securities &
Investments Mirae Asset Securities(NY)
- Mirae Asset Global Investments
- Global X
- Mirae Asset Capital Life Science
- Wealthspot
Vietnam
- Mirae Asset Securities
- Mirae Asset Finance Company
- Mirae Asset Prevoir Life Insurance
- Mirae Asset Global Investments
- Vina Digital Finance Platform
- Grooo International Joint Stock
Company Mirae Asset Alternative
Invetment VietnamMirae Asset Securities
- Ho Chi Minh representative Ofiice
Brazil
Singapore
United Arab Emirates
Mirae Asset Investment Managers
- Dubai representative Office
Ireland
United Kingdom
India
Indonesia
Japan
China
- Mirae Asset Huachen Fund
Management Mirae Asset Investment
Management(Shanghai)Mirae Asset Securitires
(Beijing representative Office)Mirae Asset Securitires
(Shanghai representative Office)
Canada
Colombia
Australia
Hong Kong SAR*
Germany
Global X ETFs - Germany Rep Office
Italy
Global X ETFs - Italy Rep Office
* Special Administrative Region of the People’s Republic of China