Research Report
Samsung Electronics (005930 KS/Buy)Capacity advantage to become more pronounced in 2027
- Author Young-gun Kim
- Date Thu Jun 25 00:00:00 KST 2026
- Stock Code 005930
- File 20260625_Samsung Electronics (005930 KS_Buy).pdf
Capacity advantage to become more pronounced in 2027
Industry-leading capacity serves as key advantage amid memory price up-cycle
We maintain our Buy rating and target price of W550,000 for Samsung Electronics (SEC). The stock is trading at a 2026F P/E of 7.2x and P/B of 3.0x, well below the sector averages (13.5x and 8.1x, respectively). Even the multiples implied by our target price (2026F P/E of 11.7x and P/B of 4.9x) remain comfortably below the sector averages.
Commodity memory prices have continued to rise. In its contract price outlook released last week, TrendForce revised up its DDR5 forecasts by 10% for 3Q26 and 14% for 4Q26, while raising its DDR4 forecasts by 15% for 3Q26 and 16% for 4Q26. Even after ASP gains of more than 50% in 2Q26, further ASP increases exceeding 20% remain possible in 3Q26 (vs. our current assumption of around 10%).
Against this backdrop of sustained price increases, we expect more than 50% of industry-wide memory shipments to be committed to big tech customers under long-term supply agreements, and SEC should be no exception. As the share of long-term agreements rises, SEC’s industry-leading DRAM and NAND capacity should make it best-positioned to capture incremental demand as supply conditions tighten.
We estimate SEC’s 2027 DRAM and NAND wafer capacity at 790,000 and 403,000 wafers/month, respectively. This would increase its share of industry capacity to 33.2% in DRAM and 27.5% in NAND (vs. 32.9% and 25.9%, respectively, in 2026). Backed by its industry-leading capacity, we believe SEC will be able to expand long-term supply agreements beyond North American customers to include customers in Greater China.
Revising down 2Q26 estimates on higher bonus provisions
We revised down our 2Q26 operating profit forecast by 14% to W84.1tr (vs. W97.7tr previously) and our 2026 operating profit forecast by 3% to W383tr (vs. W395tr previously). We previously assumed W8tr in bonus provisions in 2Q26, with the portion not recognized in 1Q26 to be accrued in subsequent quarters. We now expect the full amount to be recognized in 2Q26 and estimate the total provision at W35tr.
If SEC follows through on its plan to return 50% of cumulative 2024?26 free cash flow to shareholders, 2026 dividend yield could reach 3.6-6.0% for common shares and 6.0-9.6% for preferred shares. In addition, in 1Q26, the company acquired W28tr worth of treasury shares (at W183,000?196,000 per share) for employee compensation purposes. Although the company disclosed yesterday that no decision has been made on additional buybacks, further repurchases appear likely given the scale of the expected bonus payout.


Contact Us
- Office number1588-6800
-
- Investor Relationsirteam@miraeasset.com
- Human Resourcerecruit@miraeasset.com
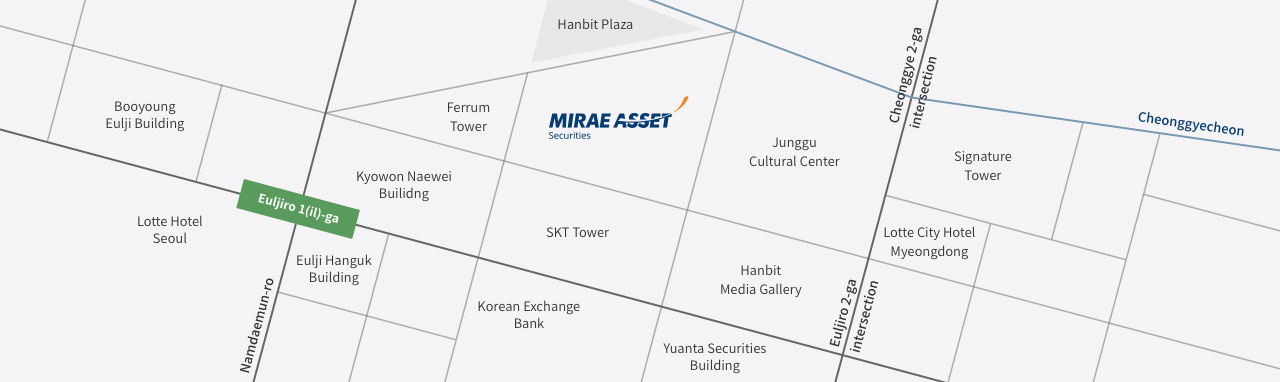
- AddressMirae Asset CENTER1 Bldg, East Tower, 26, Euljiro 5 gil, Jung-gu, Seoul 100-210
Korea (Headquarters)
Greece
Luxembourg
- Mirae Asset Global Investment(SICAV)
Mongolia
USA
- Mirae Asset Securities &
Investments Mirae Asset Securities(NY)
- Mirae Asset Global Investments
- Global X
- Mirae Asset Capital Life Science
- Wealthspot
Vietnam
- Mirae Asset Securities
- Mirae Asset Finance Company
- Mirae Asset Prevoir Life Insurance
- Mirae Asset Global Investments
- Vina Digital Finance Platform
- Grooo International Joint Stock
Company Mirae Asset Alternative
Invetment VietnamMirae Asset Securities
- Ho Chi Minh representative Ofiice
Brazil
Singapore
United Arab Emirates
Mirae Asset Investment Managers
- Dubai representative Office
Ireland
United Kingdom
India
Indonesia
Japan
China
- Mirae Asset Huachen Fund
Management Mirae Asset Investment
Management(Shanghai)Mirae Asset Securitires
(Beijing representative Office)Mirae Asset Securitires
(Shanghai representative Office)
Canada
Colombia
Australia
Hong Kong SAR*
Germany
Global X ETFs - Germany Rep Office
Italy
Global X ETFs - Italy Rep Office
* Special Administrative Region of the People’s Republic of China