Research Report
SK Telecom (017670 KS/Buy)Strong 2Q26 earnings expected; major AI data center capacity plan announced
- Author YooJin Choi
- Date Wed Jul 15 00:00:00 KST 2026
- Stock Code 017670
- File 20260715_SK Telecom (017670 KS_Buy).pdf
Strong 2Q26 earnings expected; major AI data center capacity plan announced
2Q26 preview: OP likely to beat consensus amid rising data center utilization
For 2Q26, we expect SK Telecom (SKT) to report consolidated revenue of W4.4tr (+1.3% QoQ, +2.5% YoY) and operating profit of W557.5bn (+3.7% QoQ, +64.8% YoY; roughly 3.5% above the consensus).
For SK Broadband, we estimate revenue at W1.2tr (+3.4% YoY) and operating profit at W103bn (+31.9% YoY). Earnings likely remained on an upward trend, driven by additional revenue from the Pangyo data center, net subscriber additions in the broadband business, and a higher mix of Giga internet subscribers.
AI data center capacity expansion: A key medium/long-term earnings driver
At a government briefing on Korea’s three national mega projects on Jun. 29, SKT announced plans to develop 15GW of AI data center capacity nationwide, requiring total investments of approximately W1,000tr. This would represent one of the largest AI data center build-outs in Asia, equivalent to roughly seven times the combined power capacity of all data centers currently in operation in Korea.
We estimate that the new capacity will begin coming online gradually from 2H27, reaching 5GW before expanding to 15GW by 2035. Once the funding structure, business model, and demand outlook become more clearly defined, the project should become a key driver of SKT’s medium/long-term earnings growth. We expect its contribution to consolidated revenue to begin to increase meaningfully from 2028.
Given its group-level support and unique full-stack AI capabilities spanning infrastructure, models, and services, we believe the company is well-positioned to turn its AI data center build-out into a new medium/long-term growth engine while maintaining its competitive edge as the telecom services industry undergoes structural change. We therefore continue to recommend increasing exposure to the stock.
Maintain TP of W120,000; still our top pick in the sector
We maintain our target price of W120,000 for SKT and continue to recommend the stock as our top pick in the sector. Our target price is based on the sum of SKT’s operating value (W22.5tr) and the value of its stake in Anthropic (W3.4tr).
We expect profitability in the telecom services business to continue improving through enhanced cost efficiency. At the same time, rising utilization at existing AI data centers should provide a meaningful boost to earnings.


Contact Us
- Office number1588-6800
-
- Investor Relationsirteam@miraeasset.com
- Human Resourcerecruit@miraeasset.com
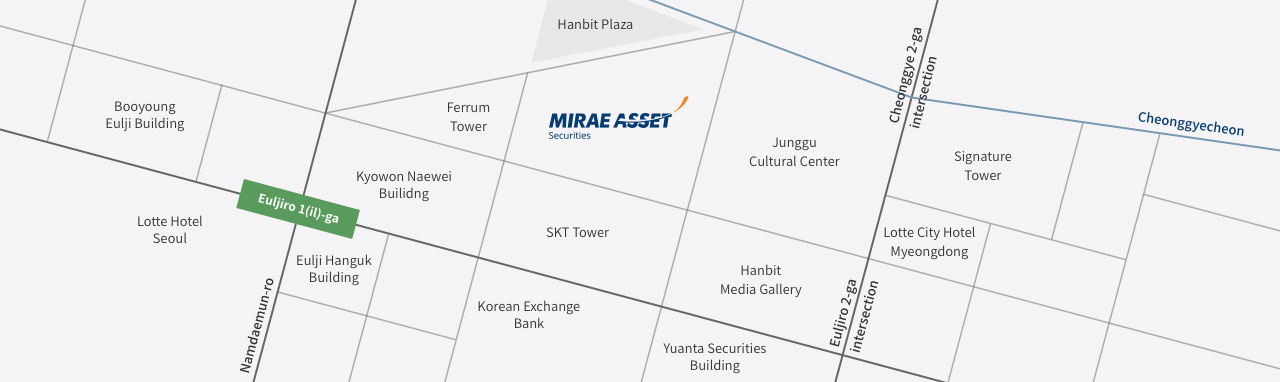
- AddressMirae Asset CENTER1 Bldg, East Tower, 26, Euljiro 5 gil, Jung-gu, Seoul 100-210
Korea (Headquarters)
Greece
Luxembourg
- Mirae Asset Global Investment(SICAV)
Mongolia
USA
- Mirae Asset Securities &
Investments Mirae Asset Securities(NY)
- Mirae Asset Global Investments
- Global X
- Mirae Asset Capital Life Science
- Wealthspot
Vietnam
- Mirae Asset Securities
- Mirae Asset Finance Company
- Mirae Asset Prevoir Life Insurance
- Mirae Asset Global Investments
- Vina Digital Finance Platform
- Grooo International Joint Stock
Company Mirae Asset Alternative
Invetment VietnamMirae Asset Securities
- Ho Chi Minh representative Ofiice
Brazil
Singapore
United Arab Emirates
Mirae Asset Investment Managers
- Dubai representative Office
Ireland
United Kingdom
India
Indonesia
Japan
China
- Mirae Asset Huachen Fund
Management Mirae Asset Investment
Management(Shanghai)Mirae Asset Securitires
(Beijing representative Office)Mirae Asset Securitires
(Shanghai representative Office)
Canada
Colombia
Australia
Hong Kong SAR*
Germany
Global X ETFs - Germany Rep Office
Italy
Global X ETFs - Italy Rep Office
* Special Administrative Region of the People’s Republic of China