Research Report
Kakao (035720 KS/Buy)Time for AI initiatives to deliver
- Author HeeSeok Lim
- Date Thu Aug 06 00:00:00 KST 2026
- Stock Code 035720
- File 20260806_Kakao (035720 KS_Buy).pdf
Time for AI initiatives to deliver
2Q26 review: In-line revenue and above-consensus OP
For 2Q26, Kakao reported revenue of W2.098tr (+9% YoY; in line with the consensus) and operating profit of W277bn (+36% YoY; 22% above the consensus). The earnings beat was mainly attributable to improved profitability at Kakao Pay driven by strong growth in financial services revenue. Kakao Pay posted revenue of W335bn (+41% YoY) and operating profit of W59bn (+528% YoY).
Platform revenue rose 17% YoY to W1.23tr, with Talk Biz revenue reaching W643bn (+12% YoY), 4% above our estimate. Meanwhile, content revenue edged up only 1% YoY to W868bn, weighed down by persistent weakness in the Story business (webtoons/web novels). Operating expenses totaled W1.82tr (+6% YoY), in line with our estimate.
Ad growth is encouraging, but AI benefits remain unclear
Display ad revenue grew 28% YoY in 2Q26, while message-based ad revenue increased 20% YoY. Notably, growing usage of content feeds within KakaoTalk is allowing new feed-based ad products to gain traction, helping to diversify the display ad segment beyond its traditional focus on Bizboard ads. At the same time, message-based ad revenue should maintain strong growth, supported by solid demand from advertisers in the financial sector.
Meanwhile, user engagement with Kakao’s AI services is improving, with Kanana’s user retention rate rising to around 80%. However, this has yet to translate into a meaningful increase in time spent on the platform. To give users more reasons to incorporate Kanana into their daily lives, Kakao plans to expand integrations with various platforms, including Coupang Eats.
Maintain Buy, but cut TP to W52,000
We lower our target price for Kakao to W52,000 (from W58,000), reflecting: 1) downward revisions to our 2027 earnings forecasts due to slowing growth in the content business; and 2) a reduction in our target P/E to 29x (from 31x). The stock is trading at a 2027F P/E of around 21x, representing its most attractive valuation on record. However, we believe momentum will remain limited until the firm demonstrates a recovery in traffic.
Unlike in the past, when ad growth was the key valuation driver, platform company valuations now hinge on the pace and profitability of AI monetization. Although competition is intense, a successful B2C AI service could generate substantially higher margins than the data center business. Ultimately, whether KakaoTalk traffic rebounds will be the key investment consideration for 2H26.


Contact Us
- Office number1588-6800
-
- Investor Relationsirteam@miraeasset.com
- Human Resourcerecruit@miraeasset.com
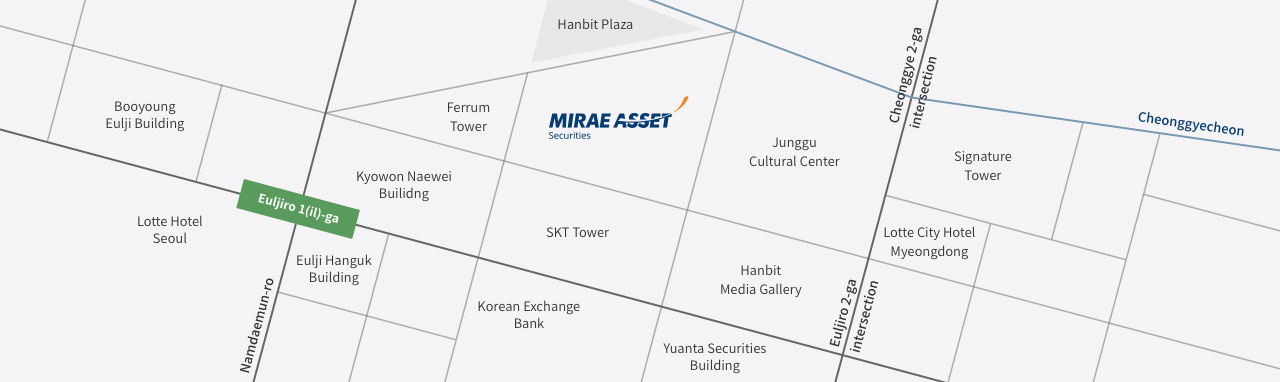
- AddressMirae Asset CENTER1 Bldg, East Tower, 26, Euljiro 5 gil, Jung-gu, Seoul 100-210
Korea (Headquarters)
Greece
Luxembourg
- Mirae Asset Global Investment(SICAV)
Mongolia
USA
- Mirae Asset Securities &
Investments Mirae Asset Securities(NY)
- Mirae Asset Global Investments
- Global X
- Mirae Asset Capital Life Science
- Wealthspot
Vietnam
- Mirae Asset Securities
- Mirae Asset Finance Company
- Mirae Asset Prevoir Life Insurance
- Mirae Asset Global Investments
- Vina Digital Finance Platform
- Grooo International Joint Stock
Company Mirae Asset Alternative
Invetment VietnamMirae Asset Securities
- Ho Chi Minh representative Ofiice
Brazil
Singapore
United Arab Emirates
Mirae Asset Investment Managers
- Dubai representative Office
Ireland
United Kingdom
India
Indonesia
Japan
China
- Mirae Asset Huachen Fund
Management Mirae Asset Investment
Management(Shanghai)Mirae Asset Securitires
(Beijing representative Office)Mirae Asset Securitires
(Shanghai representative Office)
Canada
Colombia
Australia
Hong Kong SAR*
Germany
Global X ETFs - Germany Rep Office
Italy
Global X ETFs - Italy Rep Office
* Special Administrative Region of the People’s Republic of China