Research Report
NAVER (035420 KS/Buy)Take a longer-term view
- Author HeeSeok Lim
- Date Mon Aug 10 00:00:00 KST 2026
- Stock Code 035420
- File 20260810_NAVER (035420 KS_Buy).pdf
Take a longer-term view
2Q26 review: Profitability deteriorates
For 2Q26, NAVER reported revenue of W3.39tr (+16% YoY) and operating profit of W520.3bn (flat YoY). Revenue was in line with the consensus, but operating profit missed by 8%. The core NAVER platform business posted revenue of W1.90tr (+12% YoY; in line with our estimate), with ad revenue growth slowing further (+7% YoY to W1.45tr; 2% below our estimate). Financial platform revenue totaled W470.7bn (+16% YoY; 3% above our estimate).
Operating expenses increased 20% YoY to W2.87tr (3% above our estimate). Marketing expenses rose to W604.9bn (+25% YoY, +18% QoQ), driven by increased promotions for Npay Connect, the company’s integrated offline payment terminal.
AI data center business taking shape
NAVER plans to launch AI factory services with capacity of 55MW in 1H27, expanding to 100MW by end-2027 and 200MW in 2028. It has already secured most of the data center space required for the 200MW phase. Beyond that, the company plans to scale the business to 1GW by developing its own greenfield facilities in Korea and working with global partners. The development of overseas data centers remains under discussion.
We assume AI data center revenue at W1.3tr for 2027 and W3.3tr for 2028, with an initial margin of 6?7%. For the AI factory business, NAVER plans to establish a wholly owned operating subsidiary, which will recognize computing revenue on a gross basis while paying computing expenses to an infrastructure special-purpose vehicle (SPV). NAVER could also recognize equity-method gains depending on its stake in the SPV.
Maintain Buy and TP of W280,000
While we incorporated AI data center revenue into our estimates from 2027, we maintain our target price at W280,000 (based on a 2027F P/E of 20x) to reflect higher cost estimates. The stock is trading at a 2027F P/E of 16.1x, suggesting a limited valuation burden. Additional GPUaaS order wins in 2H26 would likely help ease uncertainty over AI data center demand and support a valuation re-rating.
That said, the extent of any re-rating should remain limited until profitability in the core business begins to recover. We do not expect the AI data center business to make a meaningful contribution to earnings until 2029 or later. Moreover, profitability is poised to deteriorate in 2H26 due to both slowing ad revenue growth amid declining traffic and a surge in marketing expenses associated with the aggressive rollout of Npay Connect terminals.


Contact Us
- Office number1588-6800
-
- Investor Relationsirteam@miraeasset.com
- Human Resourcerecruit@miraeasset.com
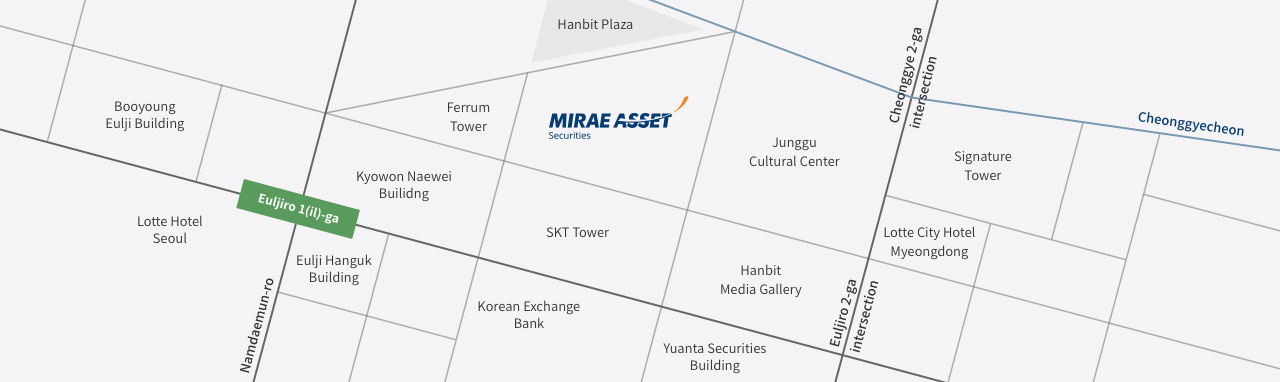
- AddressMirae Asset CENTER1 Bldg, East Tower, 26, Euljiro 5 gil, Jung-gu, Seoul 100-210
Korea (Headquarters)
Greece
Luxembourg
- Mirae Asset Global Investment(SICAV)
Mongolia
USA
- Mirae Asset Securities &
Investments Mirae Asset Securities(NY)
- Mirae Asset Global Investments
- Global X
- Mirae Asset Capital Life Science
- Wealthspot
Vietnam
- Mirae Asset Securities
- Mirae Asset Finance Company
- Mirae Asset Prevoir Life Insurance
- Mirae Asset Global Investments
- Vina Digital Finance Platform
- Grooo International Joint Stock
Company Mirae Asset Alternative
Invetment VietnamMirae Asset Securities
- Ho Chi Minh representative Ofiice
Brazil
Singapore
United Arab Emirates
Mirae Asset Investment Managers
- Dubai representative Office
Ireland
United Kingdom
India
Indonesia
Japan
China
- Mirae Asset Huachen Fund
Management Mirae Asset Investment
Management(Shanghai)Mirae Asset Securitires
(Beijing representative Office)Mirae Asset Securitires
(Shanghai representative Office)
Canada
Colombia
Australia
Hong Kong SAR*
Germany
Global X ETFs - Germany Rep Office
Italy
Global X ETFs - Italy Rep Office
* Special Administrative Region of the People’s Republic of China