Research Report
Pearl Abyss (263750 KQ/Sell)A long wait for the next catalyst
- Author HeeSeok Lim
- Date Wed Aug 12 00:00:00 KST 2026
- Stock Code 263750
- File 20260812_Pearl Abyss (263750 KQ_Sell).pdf
A long wait for the next catalyst
2Q26 review: Below-consensus results
For 2Q26, Pearl Abyss posted revenue of W192.6bn (-41% QoQ) and operating profit of W67.6bn (-68% QoQ), missing the consensus estimates by 30% and 52%, respectively. The results also fell well short of the company’s 2Q guidance provided alongside its 1Q26 earnings release (revenue in the W271.3-324.7bn range and operating profit in the W129.6-176.7bn range). The earnings weakness was driven by a sharp downward stabilization in Crimson Desert revenue.
Crimson Desert revenue fell 49% QoQ to W136.1bn. The title sold 2.11mn copies (vs. around 4mn in 1Q26), while ASP declined to around W63,000 (from W74,000 in 1Q26). Black Desert revenue fell 11% QoQ to W55bn, extending its downward trend, as the company focused on content improvements rather than large-scale updates.
Full-year guidance cut sharply amid lower expectations for Crimson Desert
Reflecting downward revisions to its assumptions for Crimson Desert, Pearl Abyss lowered its 2026 revenue guidance by 19-24% to W709.8-743.8bn and its operating profit guidance by 35-40% to W315.5-345.2bn. For 2H26, the company now expects revenue of W122-128bn from Black Desert and W66-95bn from Crimson Desert.
Pearl Abyss is seeking to revive Crimson Desert sales through a DLC release and expansion to the Nintendo Switch 2 platform. The DLC is currently under development, with the company reviewing its content direction and overall quality. More concrete details are expected in 3Q26, with a launch targeted by year-end. The Nintendo Switch 2 version is targeted for release in 1H27, with optimization work underway.
Maintain Sell; lower TP to W30,000
We believe a conservative approach remains warranted and maintain our Sell rating. We lower our target price to W30,000 (from W36,000), reflecting: 1) earnings revisions based on the Crimson Desert sales trajectory; and 2) a shift in our valuation base period from 2026F to 2H26F-1H27F. Our target P/E remains unchanged at 12x. Any delay to the DLC release schedule could pose further downside risk to the 2026 guidance.
We believe the company is entering a prolonged period without new title releases, making a further de-rating inevitable. The Crimson Desert DLC alone is unlikely to drive a meaningful recovery in revenue, and DokeV is unlikely to be released before 2H28 even if development proceeds without delays. While Plan 8 is being developed to follow DokeV, there is likely to be a two- to three-year interval between the two releases.


Contact Us
- Office number1588-6800
-
- Investor Relationsirteam@miraeasset.com
- Human Resourcerecruit@miraeasset.com
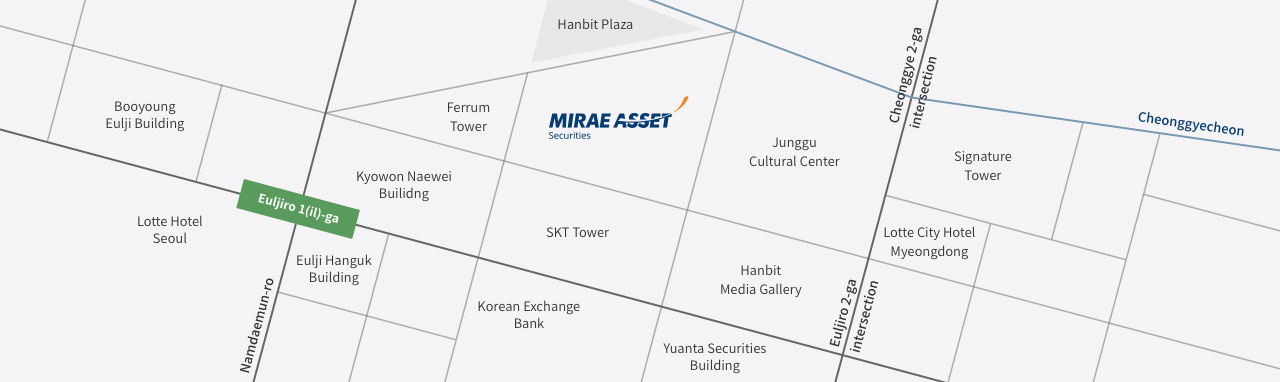
- AddressMirae Asset CENTER1 Bldg, East Tower, 26, Euljiro 5 gil, Jung-gu, Seoul 100-210
Korea (Headquarters)
Greece
Luxembourg
- Mirae Asset Global Investment(SICAV)
Mongolia
USA
- Mirae Asset Securities &
Investments Mirae Asset Securities(NY)
- Mirae Asset Global Investments
- Global X
- Mirae Asset Capital Life Science
- Wealthspot
Vietnam
- Mirae Asset Securities
- Mirae Asset Finance Company
- Mirae Asset Prevoir Life Insurance
- Mirae Asset Global Investments
- Vina Digital Finance Platform
- Grooo International Joint Stock
Company Mirae Asset Alternative
Invetment VietnamMirae Asset Securities
- Ho Chi Minh representative Ofiice
Brazil
Singapore
United Arab Emirates
Mirae Asset Investment Managers
- Dubai representative Office
Ireland
United Kingdom
India
Indonesia
Japan
China
- Mirae Asset Huachen Fund
Management Mirae Asset Investment
Management(Shanghai)Mirae Asset Securitires
(Beijing representative Office)Mirae Asset Securitires
(Shanghai representative Office)
Canada
Colombia
Australia
Hong Kong SAR*
Germany
Global X ETFs - Germany Rep Office
Italy
Global X ETFs - Italy Rep Office
* Special Administrative Region of the People’s Republic of China