Research Report
SK Biopharmaceuticals (326030 KS/Buy)Two concerns addressed; focus now turns to RISE3 data
- Author Seung-min Kim
- Date Thu Aug 27 00:00:00 KST 2026
- Stock Code 326030
- File 20260827_SK Biopharmaceuticals (326030 KS_Buy).pdf
Two concerns addressed; focus now turns to RISE3 data
Raise TP to W160,000 (from W150,000); maintain Buy
We are positive on SK Biopharmaceuticals’ decision to in-license opakalim, a Kv7 activator being developed to treat epilepsy, from Biohaven. The deal creates a pathway for the company to transition from directly selling a single product (Xcopri) in the US to operating a multi-product portfolio. This follows the growth model adopted by established global biopharmas such as Vertex Pharmaceuticals, Jazz Pharmaceuticals, and UCB. If opakalim reaches the market, SK Biopharmaceuticals would become the first and only Korean biopharma company to directly commercialize multiple drugs through its own US sales platform.
The deal mitigates two concerns that had weighed on the company’s valuation: 1) the absence of a follow-on product to Xcopri; and 2) the competitive threat posed by Xenon Pharmaceuticals'' azetukalner. Accordingly, we removed the discount previously applied to our target multiple and raised our target price to W160,000 (from W150,000). That said, our target price does not yet directly incorporate opakalim’s rNPV or expected changes in net cash/debt following the transaction’s closing. We plan to assess these factors after the release of data from RISE3, the registrational epilepsy trial for opakalim, which is expected by year-end.
Through Xcopri, SK Biopharmaceuticals has already built relationships with US prescribers, secured formulary coverage, established specialty pharmacy channels, and developed its own medical affairs and sales capabilities. If approved, opakalim would leverage this existing infrastructure, limiting incremental selling expenses. The two products would also have distinct positioning, with efficacy as Xcopri’s key differentiator and tolerability as opakalim’s.
Xcopri demonstrated strong seizure reduction and high seizure freedom rates in its registrational trials. It is generally regarded as having the highest seizure freedom rate among epilepsy treatments. Meanwhile, opakalim showed low rates of central nervous system (CNS) adverse events (e.g., dizziness and somnolence) in a long-term extension study, suggesting the potential for a superior tolerability profile. While randomized registrational data for opakalim are not yet available, confirmation of this tolerability profile in RISE3 could support its use at earlier stages of treatment.
Management stated that its due diligence included a review of opakalim’s long-term extension data in focal seizures, data from patients with genetic variants, data in generalized seizures, and preclinical findings. The company believes opakalim could be competitive if its tolerability advantage is maintained, even if its efficacy proves comparable to or slightly weaker than that of azetukalner. The key question is whether RISE3 will demonstrate both competitive efficacy and a low incidence of CNS adverse events. Consensus estimates put azetukalner’s 2035 sales at approximately US$2.5bn, while Xenon Pharmaceuticals’ market cap stands at around US$6bn. The current 2035 consensus sales estimate for opakalim is approximately US$1bn.


Contact Us
- Office number1588-6800
-
- Investor Relationsirteam@miraeasset.com
- Human Resourcerecruit@miraeasset.com
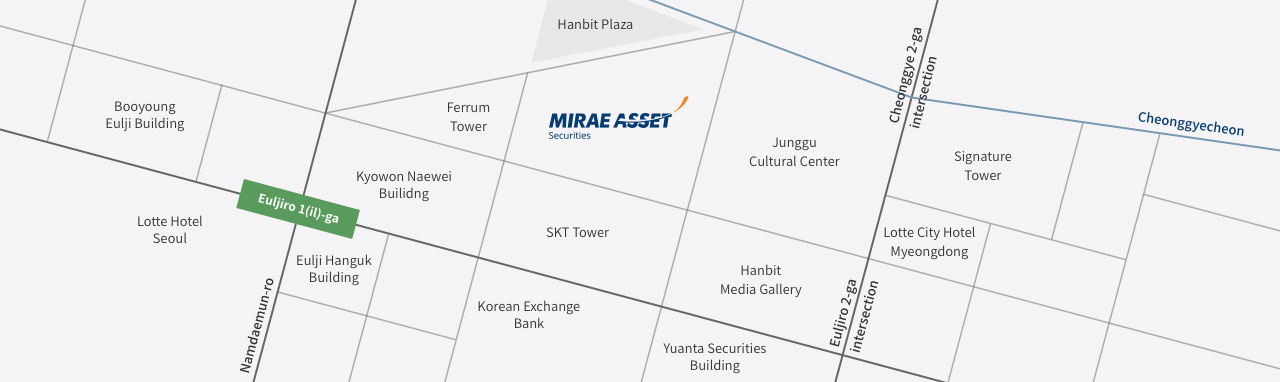
- AddressMirae Asset CENTER1 Bldg, East Tower, 26, Euljiro 5 gil, Jung-gu, Seoul 100-210
Korea (Headquarters)
Greece
Luxembourg
- Mirae Asset Global Investment(SICAV)
Mongolia
USA
- Mirae Asset Securities &
Investments Mirae Asset Securities(NY)
- Mirae Asset Global Investments
- Global X
- Mirae Asset Capital Life Science
- Wealthspot
Vietnam
- Mirae Asset Securities
- Mirae Asset Finance Company
- Mirae Asset Prevoir Life Insurance
- Mirae Asset Global Investments
- Vina Digital Finance Platform
- Grooo International Joint Stock
Company Mirae Asset Alternative
Invetment VietnamMirae Asset Securities
- Ho Chi Minh representative Ofiice
Brazil
Singapore
United Arab Emirates
Mirae Asset Investment Managers
- Dubai representative Office
Ireland
United Kingdom
India
Indonesia
Japan
China
- Mirae Asset Huachen Fund
Management Mirae Asset Investment
Management(Shanghai)Mirae Asset Securitires
(Beijing representative Office)Mirae Asset Securitires
(Shanghai representative Office)
Canada
Colombia
Australia
Hong Kong SAR*
Germany
Global X ETFs - Germany Rep Office
Italy
Global X ETFs - Italy Rep Office
* Special Administrative Region of the People’s Republic of China